Saudi Arabia entered the war. The index cannot see it yet.
US and Saudi forces struck Iran-backed militias in Iraq on 29 July. Every series in the Stress Index predates it — the oldest by 89 days. What that hides.

American and Saudi forces struck Iran-backed militias in Iraq on 29 July, ending a short pause in a war that began on 28 February. The Stress Index reads 45.4 — Normal — and that reading is built entirely from observations made before the strikes. The oldest of its five inputs is 89 days old. This piece is about what the index can and cannot see today, because the gap between those two things is where most bad analysis of this war is going to come from.
What is established, and what is reported
Two categories, kept separate throughout.
Reported by news organisations, not independently verifiable here. Iran fired on American forces overnight; the United States and Saudi Arabia conducted joint strikes on Tehran-backed militias in Iraq (Bloomberg, CNN). Brent futures rose 7.2% to $90.12 and WTI 6.6% to $84.46 (CNBC).
Re-fetchable from public series. Everything in the tables below, each with a named series and an observation date.
The distinction is not pedantry. The $90.12 figure is a futures contract. The series this site’s energy component actually reads is Brent spot as published by the EIA, and its most recent observation is $86.99, dated 20 July — nine days before the strikes. Those two numbers describe different instruments on different dates. Treating them as one number is the most common error in energy commentary during a shock.
Not one input can see 29 July
| Component | Weight | Score | Driving series | Latest observation | Behind |
|---|---|---|---|---|---|
| Financial conditions | 30% | 21.3 | STLFSI4 / VIXCLS | 24 Jul / 28 Jul | 5d / 1d |
| Energy shock | 25% | 85.8 | DCOILBRENTEU | 20 Jul | 9d |
| Global trade activity | 25% | 10.4 | IGREA | 1 May | 89d |
| Dollar pressure | 20% | 74.8 | DTWEXBGS | 24 Jul | 5d |
The VIX is the only input that publishes without delay, and even so its most recent close — 18.21 on 28 July — is from the day before the strikes. It is a low reading: the volatility market was calm on the eve of an escalation.
On the measured lags, 29 July will reach each series on roughly these dates: the dollar index around 2 August, Brent spot around 6 August, the St. Louis Fed stress index around 2 August, and global trade activity not until late October. An index built from public data is a rear-view instrument. It is better to say so than to imply otherwise by publishing a number without its vintage.
The escalation lands on an energy component already at Severe
This matters more than the headline reading suggests.
The index sits at 45.4, down 2.0 points on the month and 3.6 on the week, though up 14.3 on the year. Underneath, the energy component is at 85.8 — Severe, and it has been above 79 for five consecutive months. Dollar pressure is at 74.8, Elevated. What holds the headline number down is financial conditions at 21.3 and trade activity at 10.4.
That fall is worth stating plainly. The St. Louis Fed stress index printed −0.8263 for 24 July against −0.7011 previously — less financial stress, not more. The composite fell from 50.6 on 23 July to 45.5 on 24 July, a drop of 5.1 points in a session, and has sat near there since. On the eve of an escalation, this index was going down.
The escalation is therefore not arriving at a calm energy market and disturbing it. It is arriving at a market already pricing violence, where the component has limited room to rise before it saturates. A percentile score cannot exceed 100, and 85.8 is close enough that a large move in Brent will register as a smaller change in the index than the move itself warrants. This is a known property of a percentile-ranked measure, and it argues for reading the underlying series directly during a shock rather than the composite.
The routing story the price does not tell
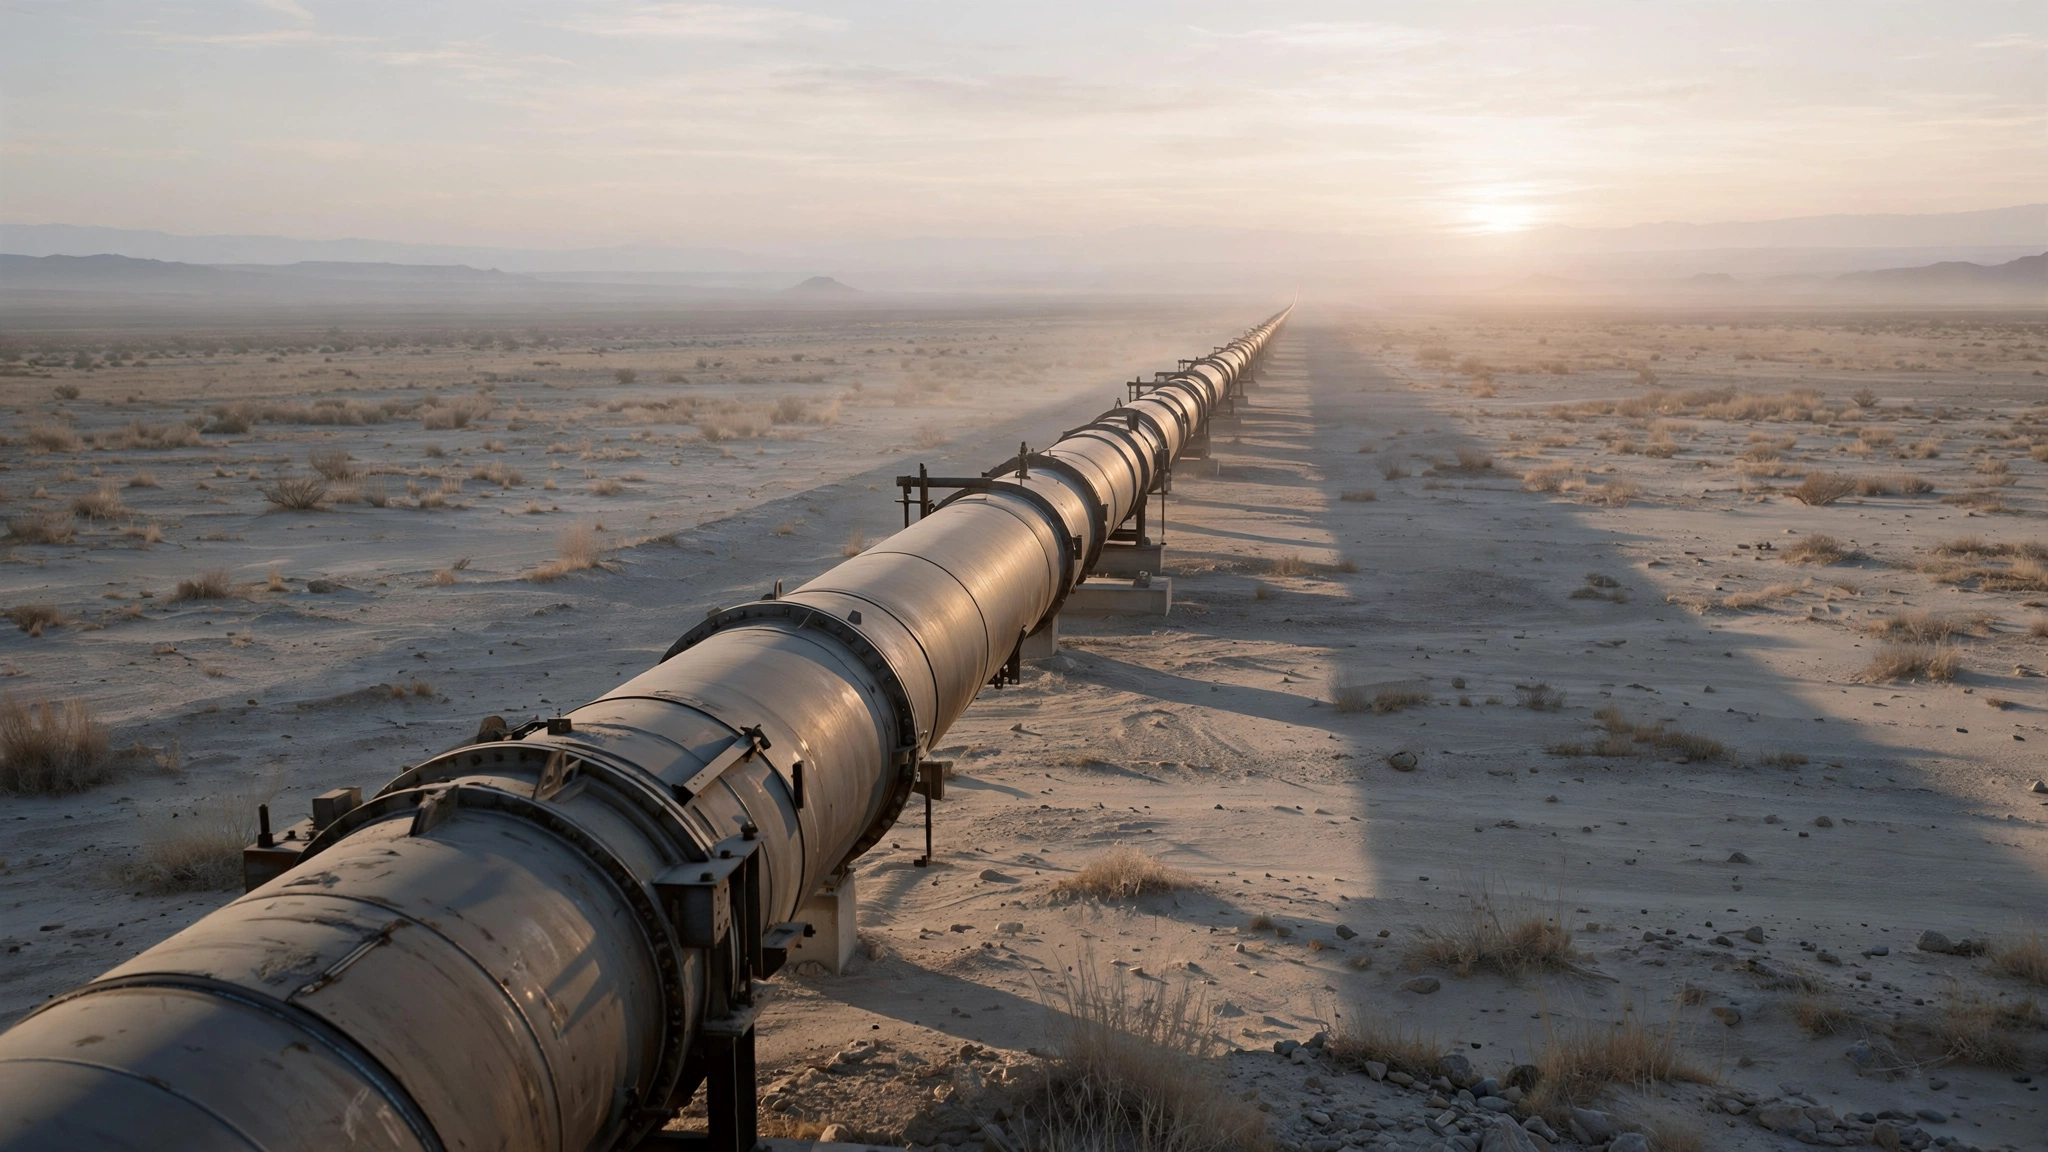
The more consequential development is not the strike. It is where Saudi oil physically leaves the country.
Reporting establishes a round trip over five months. Saudi Arabia paused loadings at its Gulf terminals of Ras Tanura and Juaymah in March after tanker traffic through Hormuz fell, and redirected a substantial share of exports through the East-West pipeline to Yanbu on the Red Sea. Loadings at Ras Tanura resumed in late June after a near four-month halt (CNBC). Red Sea crude flows then hit a record in the weeks before the Houthis announced they would block Saudi shipments (Bloomberg).
That reroute is what kept crude from pricing a genuine supply loss through the spring. The kingdom had two outlets and could shift between them.
The change worth tracking is that both are now contested at once — Hormuz by Iranian action, the Red Sea by the announced Houthi blockade. A pipeline that bypasses a chokepoint is only a fallback while its destination is open. None of the series in this index measures pipeline routing or terminal loadings; that information exists only in commercial tanker-tracking data and in reporting.
What this data cannot settle
It cannot say whether the 29 July strikes will show up as sustained stress or as a spike that decays. The index’s energy component reads 20-day realised volatility and the 63-day absolute move, both of which mechanically incorporate a shock over weeks, not hours.
It cannot separate a supply disruption from a risk premium. Brent rising does not distinguish between barrels not arriving and buyers paying more for barrels that do.
It cannot confirm any figure in the reported category above. This site did not observe the strikes, the sortie counts, or the intraday futures prints, and the sources for those are named so a reader can weigh them directly.
And it cannot see today. That is the honest position on 29 July, and it will stay the honest position until roughly 6 August for energy.
What to watch
The VIX, the shortest-lagged input, last at 18.21 on 28 July. It is the single input that will register 29 July before any other. A close above the 56th percentile of its five-year range would be the first hard evidence in this dataset that the escalation reached financial conditions rather than staying in the oil price.
Brent spot on FRED, $86.99 as of 20 July, expected to cover 29 July around 6 August. The gap between that eventual print and the $90.12 futures level being quoted today is the measure of how much of the move was positioning rather than physical.
Whether the Red Sea route stays open. Saudi export capacity through Yanbu is the mechanism that absorbed the March disruption. If both outlets are constrained simultaneously, the energy component has a path above 90 that it did not have in March — and this index has spent 20 of 221 months with energy above 80 and the dollar above 70 at the same time.